Previously I talked a little about commodity stocks. I came
across this rather interesting article on Seekingalpha.com,
which prompted me to share this information with my readers.
I have been long
on Oil and Gas for some time but stayed out because it was too expensive, but
the 2008 market crash gave me an opportunity to get into ExxonMobil (XOM).
Anyways the original author of the article has some very
interesting graphs on energy demand and population growth predictions till
2040. See below graph 1-World energy Consumption and graph 2- World population
growth:
 |
| Graph 1: World Energy Consumption |
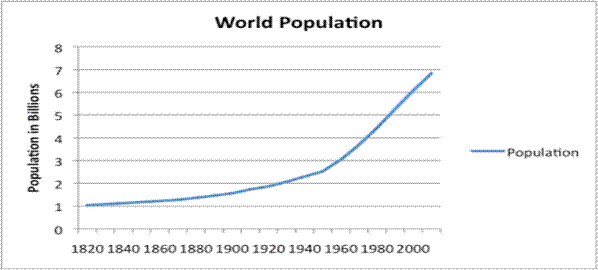 |
| Graph 2: World population growth |
There is a huge correlation and we have a reason to be
bullish about companies such as ExxonMobil who are extracting and supplying
these commodities. Over the last 100 years, world population has increased 7
times, and it is headed towards 9 Billion by 2040. Although I may not agree
totally with this figure, I still agree that population is headed higher.
Side note: I still remember while I was studying a Sustainable
Engineering module in University, world population is expected to hit 10
Billion by 2030 then start declining. This is unsustainable, because Earth’s
resources cannot continue to support such a large population; famine, draught,
disease and war will eventually reduce population growth to a negative.
Back to topic, ExxonMobil published their 2013
Energy Outlook , which predicts 9 billion people by 2040 for some reason. Energy
demand is going to increase exponentially because of two main drivers:
- Population growth
- Per Capita consumption growth
For a long term investor, it’s a clear cut decision to get
on the bandwagon without worrying about day to day price fluctuations. However I
suggest valuating energy companies such as ExxonMobil before taking any positions.
I value XOM @ $94 currently but actually wouldn’t pay $90/share right now. It’s
not worth the risk for me. I would rather wait and see if I can get in @ below
$65/share.
Anyway WHY EXXONMOBIL? The original author also shared these
graphs below comparing shareholder distributions among energy companies:
 |
| Graph 3: Comparison of Shartholder distributions |
 |
| Graph 4: Distribution yield of ExxonMobil |
ExxonMobil has a whopping! distribution yield of 7% over the past 5
years. Keeping in mind increasing energy demand over the next 30 years, and
relative stability of XOM as a company makes it a good investment of choice. Just look at their historical chart below:
 Very rarely does it drop tremendously low. in fact it has been trading in a parallel line since 1960s. I would suggest taking advantage of every market crash and accumulating its stocks over time. But of course, dont take my word for it...do your own research first. :)

Original Article by DevonShire can be found at address below:
http://seekingalpha.com/article/1293481-exxon-mobil-sports-a-juicy-and-reliable-total-distribution-yield-over-7
Disclaimer: I have a small position in ExxonMobil (XOM) and right now I am adopting a “hold and see” attitude. However I have no plans to initiate any positions within the next 72 hrs and highly recommend you do your own research to determine your own suitable entry and exit positions.

